There are several monetary first time home buying tips to consider as you prepare to apply for a home loan. Make sure you’re financially prepared to make a down payment on your new house, as requiring 0% down is truly a rarity. In general, you should be prepared to pay at least 5% of your home’s price toward the purchase. However, some loan programs allow for 3 to 3.5% instead, depending on the size of the loan and your credit history. In addition, if you are unable to put down 20% or more, you may be required to use mortgage insurance to take out a home loan. This is a very common procedure that can be included in your monthly mortgage payment to keep things simple for homeowners.
October 18, 2026
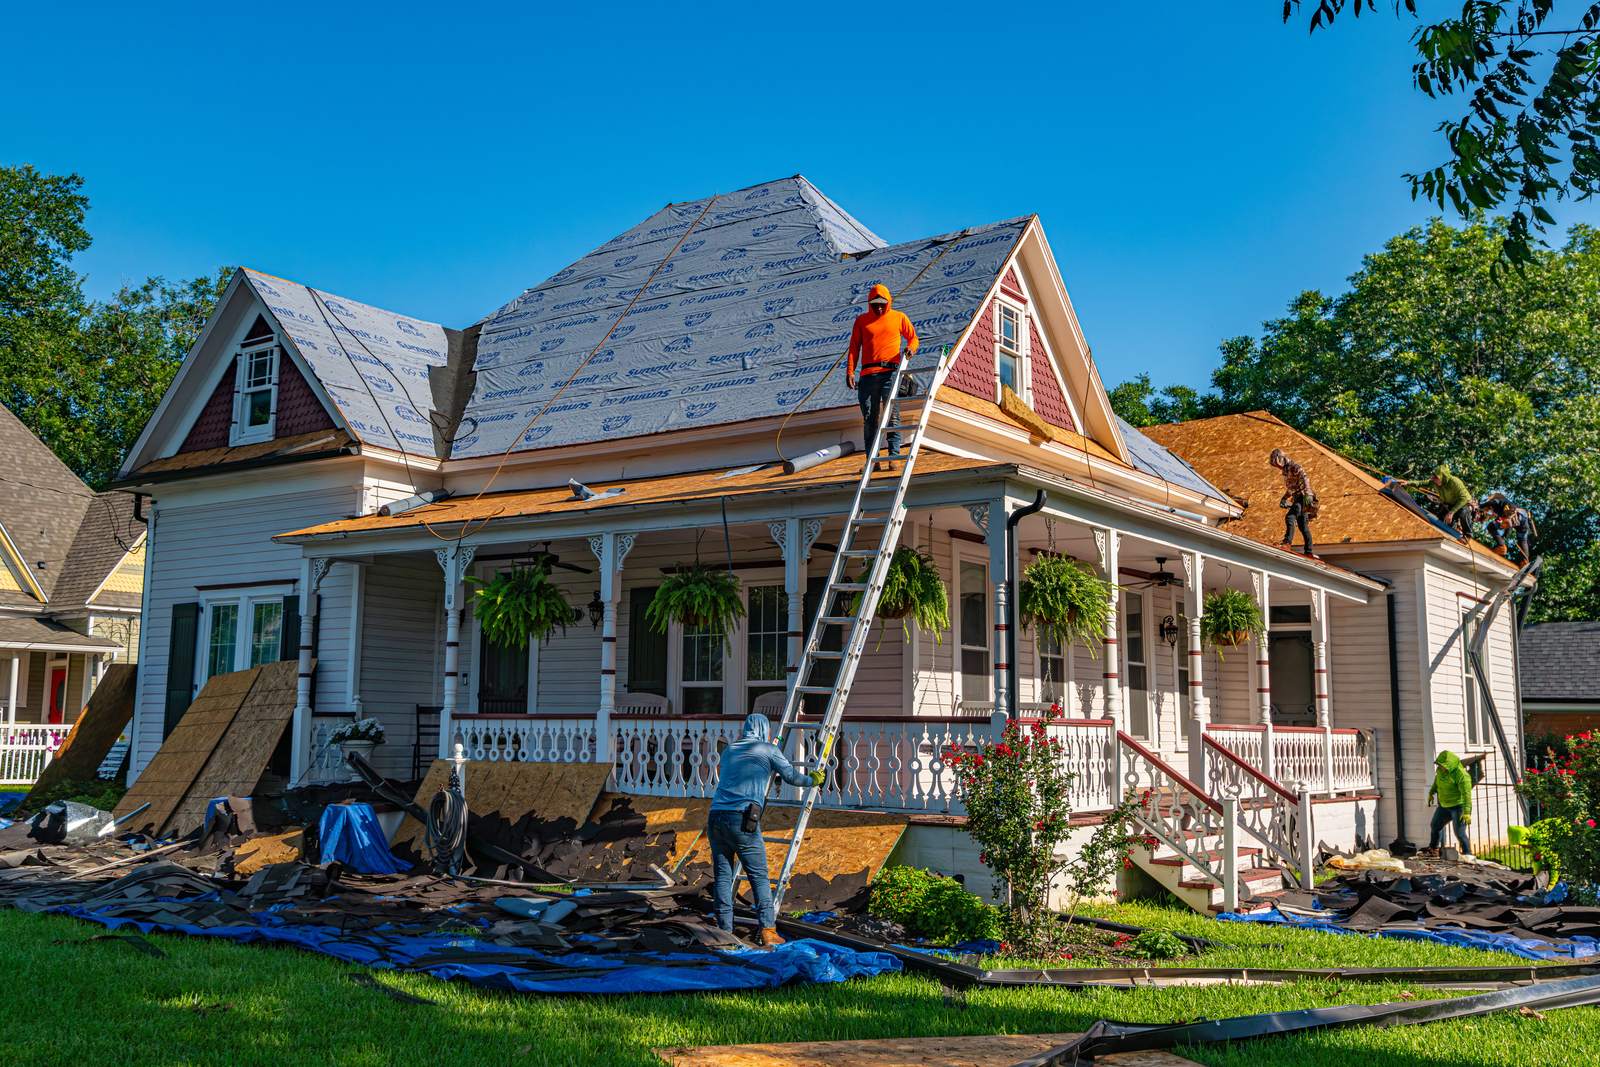
What Not to Fix When Selling a House in Brooklyn: Repairs to Skip, Make or Disclose Before You Sell Your Home
Skip the big cosmetic projects. Fix what is broken or unsafe, clear any open city violations, and disclose what you know before you sell your home. That matters more in Brooklyn than almost anywhere. The...